
How to stress test a portfolio
Dr. Mira Sol, data desk“See the gold ring? That is the bottom: −22.8% on 8 Apr 2025, back at its high in 7 months. How deep it fell and how long the climb back took: that is the risk you actually live through.”
Source: FMP daily closes, dividend-adjusted, as of 19 Nov 2026. Sample portfolio of six US stocks, $100,000 on 22 Nov 2021.
Replay a real market fall on your holdings, then scale it to a round number with beta. The result is a dollar loss you can picture before it happens.
A stress test asks one thing: if a bad stretch came back, how much would this portfolio lose? Two ways to ask it, both worked on real prices.
1Replay a fall that really happened
The S&P 500’s deepest slide in these five years ran from 3 Jan 2022 to 12 Oct 2022: −24.5%. Here is what each of our six stocks did over exactly those dates.
Source: FMP daily closes, dividend-adjusted, 22 Nov 2021 to 19 Nov 2026. Swing and shares use the last 12 months of daily moves.
Mixed together at the sample weights, the portfolio would have lost −21.2%, about −$21,215 on $100,000, leaving $78,785.
2Scale it to any market fall
History only has the falls it had. For a round number, multiply the fall by beta. At 0.68, this portfolio has moved about 0.68% for every 1% the S&P 500 moved over the last year.
Source: FMP daily closes, dividend-adjusted, 22 Nov 2021 to 19 Nov 2026. Swing and shares use the last 12 months of daily moves.
Beta is measured in a normal year. In a crash, stocks tend to move together more, so treat the gold bars as a floor, not a promise.
3See where the loss comes from
Dollars lost depend on the fall and on how much money sat in each stock. In the replay, Nvidia cost the most: −$9,269.
Source: FMP daily closes, dividend-adjusted, 22 Nov 2021 to 19 Nov 2026. Swing and shares use the last 12 months of daily moves.
| Holding | Put in | Fall | Dollars lost |
|---|---|---|---|
| NvidiaNVDA | $15,000 | −61.8% | −$9,269 |
| MicrosoftMSFT | $20,000 | −32.1% | −$6,424 |
| AppleAAPL | $25,000 | −23.7% | −$5,920 |
| JPMorgan ChaseJPM | $15,000 | −33.9% | −$5,085 |
| Johnson & JohnsonJNJ | $15,000 | −3.3% | −$494 |
| Exxon MobilXOM | $10,000 | 59.8% | $5,977 |
Source: FMP daily closes, dividend-adjusted, 22 Nov 2021 to 19 Nov 2026. Swing and shares use the last 12 months of daily moves.
If one line in that table would keep you up at night, that is the holding to look at, not the whole portfolio.
Run this on your holdings. Portfolio Scanner runs your own holdings through the same kind of scenarios.
Where a stress test goes wrong
It only knows the past
A replay holds the falls that happened. A scenario with no history (a new kind of crisis) has no dates to replay.
Beta bends in a crash
Beta is one straight line through a year of days. In a sharp sell-off most stocks move together, so a beta estimate tends to show a smaller loss than the one you get.
It is not a forecast
A stress test says what a fall would cost, not whether one is coming. It is for sizing: is that dollar figure one you can live with?
Now run it on your own holdings
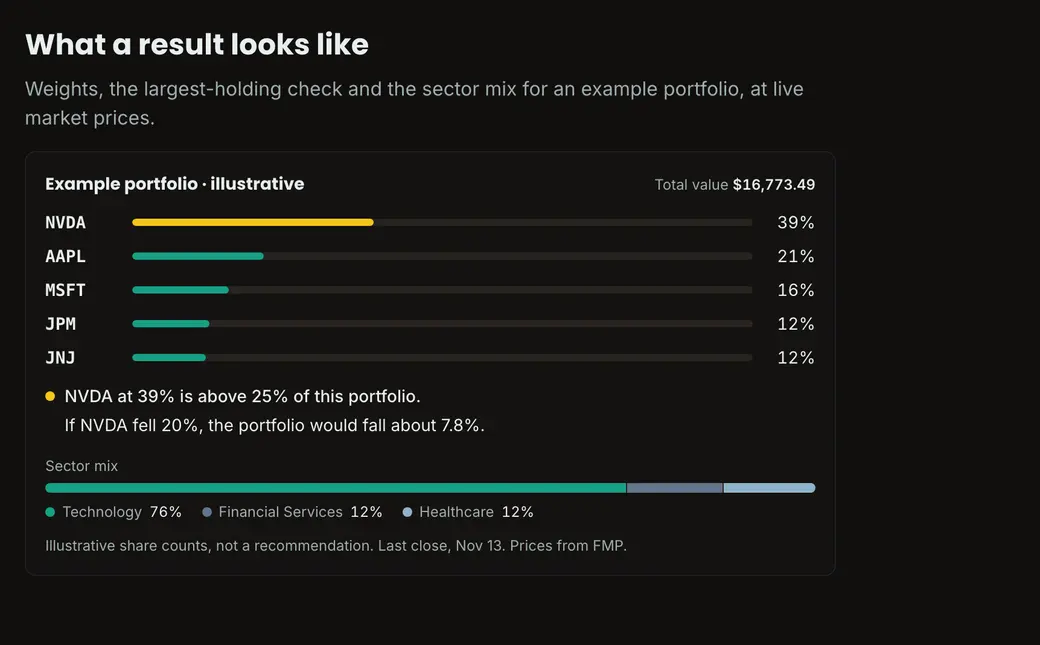
Portfolio Scanner puts your own holdings through market scenarios and shows the loss by holding, dated.
Read next
- How to analyze portfolio riskWho in the portfolio carries the swing. 4 min
- Portfolio risk, measured three waysHow bumpy, how deep, how fast back. 4 min
- What is drawdown?The fall from a high, in one picture. 3 min
Where these numbers come from
The sample: Apple 25%, Microsoft 20%, Nvidia 15%, JPMorgan Chase 15%, Johnson & Johnson 15%, Exxon Mobil 10%. It is an example to measure, not a pick.
Every figure comes from daily closing prices adjusted for dividends and splits, 22 Nov 2021 to 19 Nov 2026, from FMP. The drawdown line is buy-and-hold from day one; swing, beta and shares hold the weights fixed and use the last 12 months.
A holding’s share of the swing is its weight times how it moved with the whole portfolio, divided by the portfolio’s variance. The shares add up to 100%.
This is educational content, not investment advice. Past performance does not guarantee future results.